Where mortgage leads come from, and what origin predicts
The honest taxonomy of where a purchased mortgage lead originates, from a vendor's own ads to trigger data, and why origin predicts the call better than price does.
Updated October 24, 2026
A purchased mortgage lead comes from one of a handful of places: a vendor's own advertising, a co-registration or incentivized form, an aggregator marketplace reselling one inquiry, list or skip-traced data with no inquiry at all, or a lead that already changed hands. That origin predicts whether the person remembers asking, which matters more than price.
The origins, compared
Each origin sits at a different distance from an actual request for contact. A vendor's own landing page captures someone who asked directly. Co-registration and incentivized forms capture someone doing something else. Aggregator marketplaces and list data sit furthest out, sometimes after several resales.
| Origin | What happened | Remembers asking | The call |
|---|---|---|---|
| Own advertising | Filled vendor's own form | Usually | Normal opening |
| Co-registration | Checked a box mid-task | Rarely | Confused, denies |
| Aggregator resale | One form, several buyers | Sometimes | Expects other callers |
| List, skip-traced | Built from records | No | Defensive, unaware |
| Multi-hand resale | Changed hands again | Unlikely | Already pitched |
Facebook lead form or landing page: where our leads come from
Our own leads sit in the first row of that table. They come from paid ads we run and pay for ourselves, mostly on Facebook and Instagram, and reach us one of two ways: through the lead form that opens inside the ad, or through our own landing page that the ad clicks through to. Either way, the person answers the questions themselves. What differs is what travels with the lead.
| Our landing page | Lead form inside the ad |
|---|---|
| They click the ad and answer on our own page. | They answer inside the ad, without leaving Facebook or Instagram. |
| Before delivery, a text with a six-digit code they have to type back. | Their answers reach us from the ad itself. |
| Can carry a ZIP code, so it can fill an order limited by ZIP. | No ZIP code, so an order limited by ZIP receives landing-page leads only. |
| Consent: a box they tick themselves, with a TrustedForm certificate pulled on request. | Consent: where the form shows a consent box, the wording and their answer are stored with the lead. |
On the call, a borrower who answered the form inside the ad never left Facebook or Instagram, so they may not remember visiting a website. That is why some leads say they never filled out a form.
What our ads say to the homeowner
We write our ads to lead with the homeowner's goal, not a rate. The two below name a situation the person is in, a goal they have and a qualifier, such as a credit range or the programs that fit, and then invite them to check whether they qualify. We think an ad that names the goal brings in someone who already wants the loan, not someone curious about a number.
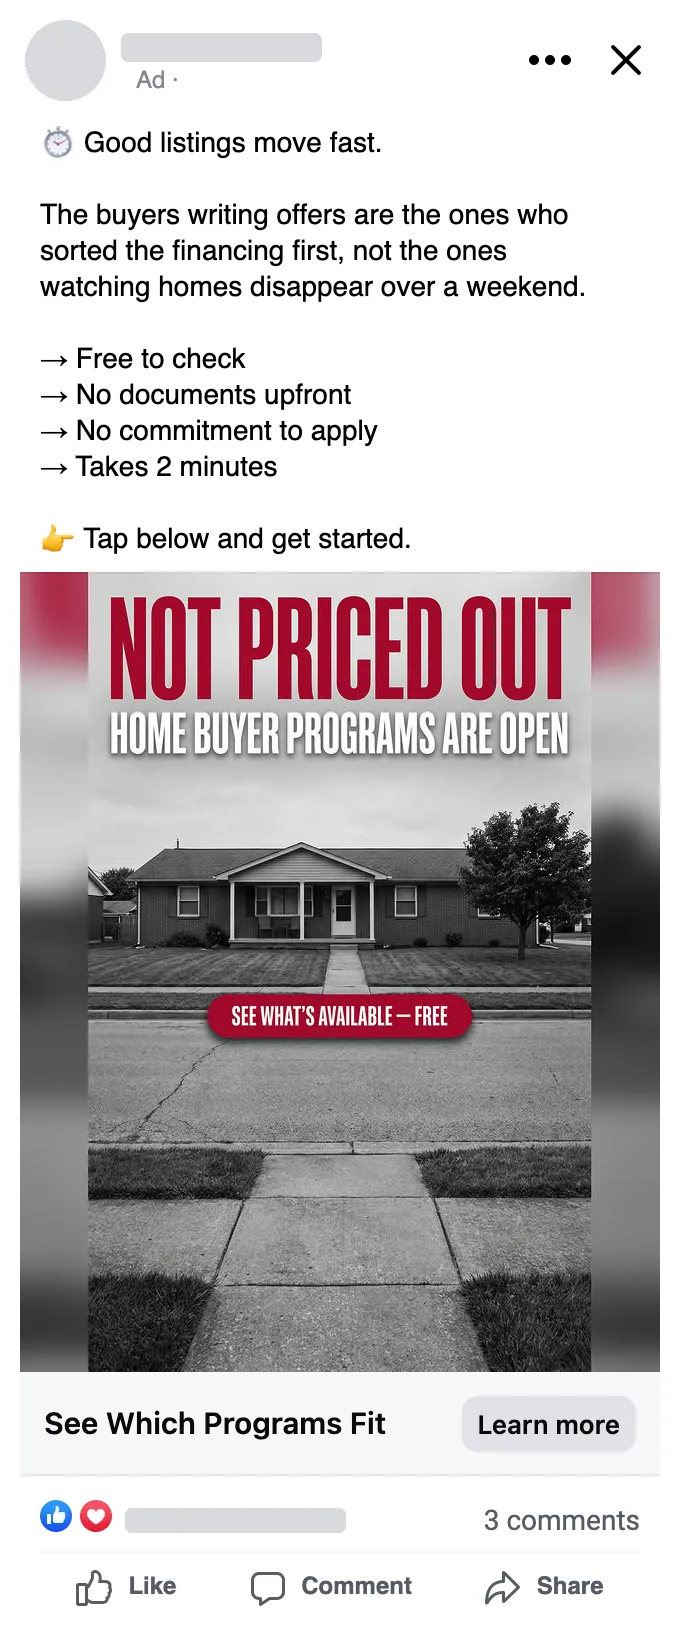
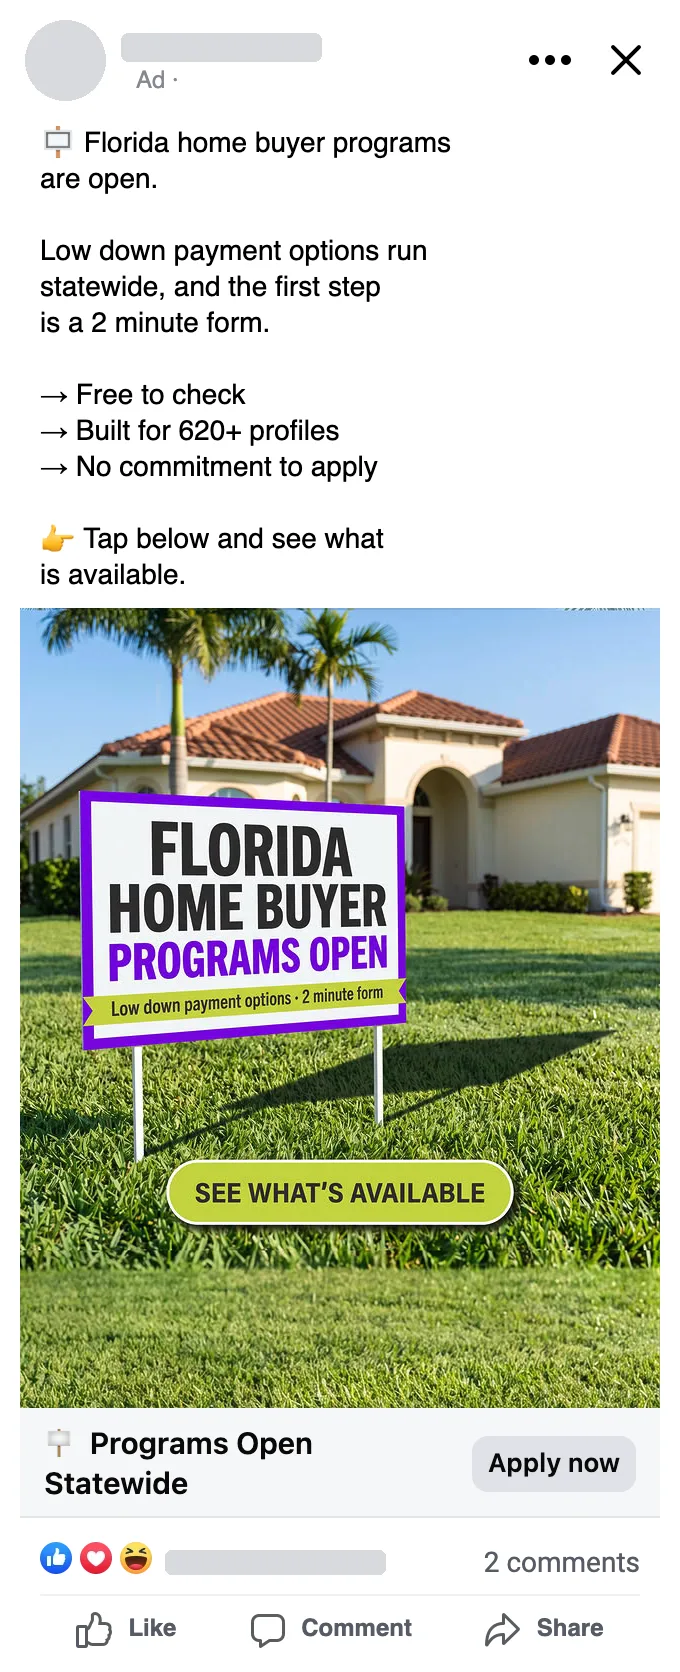
The other style is the "compare rates" or "see your estimate" ad, which talks around the goal. In our view a curious person clicks it without deciding anything, it is cheaper to run and it fills a list with lower-intent leads, which is why many vendors run it. One question loan officers bring to our calls is whether our leads are just people curious about rates.
| "Compare rates" style (generic examples) | Our hooks (live ads above) |
|---|---|
| Compare today's mortgage rates in 60 seconds | Good listings move fast. |
| See your estimated payment, no credit check | Not priced out. Home buyer programs are open. |
| Get your free quote from multiple lenders | Florida home buyer programs are open. |
| How much house can you afford? Find out instantly | Built for 620+ profiles. |
This is our view, not a measurement. We have not run a controlled test of one style against the other, so we publish no figure for the difference. What you can check is the ad itself: ask any vendor to show you the ads behind its leads.
Why the trigger lead is the clearest example
A trigger lead makes the distance visible without speculation. A credit bureau notices a hard pull tied to a mortgage inquiry and sells that trigger to other lenders within hours, before the borrower has chosen anyone. The person answering did not ask this caller anything. Congress closed that channel through H.R. 2808, the Homebuyers Privacy Protection Act, and the same distance shows up, milder, in co-registration and list data.
Source: Homebuyers Privacy Protection Act, Public Law 119-36, approved 5 September 2025. govinfo.gov · Section 3 sets the effective date at 180 days after enactment, which counts out to 4 March 2026. A good deal of trade coverage prints 5 March instead, and the statute is what we follow. Worked through in what the trigger lead ban stopped.What this means for buying leads
A vendor's answer on where a lead comes from is worth more than its answer on price. The Federal Communications Commission's December 2023 order on unwanted calls described lead-generated communications, the aggregator and resale kind, as a large share of what it was trying to stop, built on flimsy claims of consent. Buying leads without asking about origin means buying that distance sight unseen.
Source: FCC 23-107, Second Report and Order, CG Docket Nos. 02-278 and 21-402, adopted 13 December 2023, at paragraph 30. The order itself was later vacated, which does not touch the description quoted here. Taken apart in what shared leads do to a borrower.There is no published breakdown of what share of purchased mortgage leads fall into each origin, and no measured contact-rate gap between them. Vendors do not report their own mix, and that gap would settle this question with data instead of description.
Related: where to buy purchase leads, our disclosed comparison of fifteen named lead sources and the trigger lead ban.
Questions this page answers
A vendor running its own advertising to its own form, a co-registration or incentivized form where the mortgage question sat inside a survey or sweepstakes, an aggregator marketplace that resells one inquiry to several buyers, list or skip-traced data built from public or purchased records with no form at all, and leads that already passed through more than one broker before reaching a buyer. Price does not sort these. Origin does, because it decides whether the consumer remembers asking anyone to call.
No. A form is the visible part, and it can mean very different things depending on what sat around it. A person who searched for a mortgage and filled out a lender’s own page did something specific and remembers it. A person who was entering a sweepstakes and left a mortgage checkbox ticked did something else entirely. List data and skip-traced records skip the form altogether, built instead from records the consumer never touched. All three can end up called "a lead."
Because accuracy and memory are different things. A record can have the right name, phone number and loan amount and still belong to someone who has no idea why a lender is calling. That mismatch is what drives a hostile opening, a short call and a low contact rate, regardless of how clean the underlying data looks. A loan officer paying for leads is really paying for a first few seconds of attention, and origin is what decides whether those seconds are available at all.
Some are. Our leads come from paid ads we run and pay for ourselves, mostly on Facebook and Instagram, and reach us one of two ways: through the lead form that opens inside the ad, or through our own landing page that the ad clicks through to. A landing-page lead also gets a text with a six-digit code they have to type back before anything is delivered.
Not on our ads. A lead from the lead form inside our Facebook ads carries no ZIP code, so an order limited by ZIP code receives landing-page leads only.
We write our ads to lead with the borrower's goal, not a rate. The ones shown on this page name a situation the person is in, a goal they have and a qualifier, such as a credit range or the programs that fit, and invite them to check whether they qualify. We think that brings in people who want the loan rather than people curious about a number. That is our view from running the ads and from calls with loan officers, not a measured result: we have not tested one style against the other.
Buying questions rather than research ones are answered on the FAQ, and anything that is not there gets asked on a call.
More in Resources
Why a lead says they never filled out a form
Six genuinely different causes produce one identical sentence on a call, and the fix is different for each of them.
AnswersQuestions to ask before you buy mortgage leads
Sixteen questions to put to any mortgage lead vendor, from cost per funded loan and what is self-reported to an independent penetration test and what happens to a bad lead, each with our answer, then the questions for purchase, cash-out and HELOC leads and the first order that answers what they cannot.
AnswersWhat happens after you buy mortgage leads: onboarding, step by step
A short form after payment, a 20 to 40 minute onboarding call, launch, most often on a Monday, and first leads usually 24 to 48 hours after launch. Every step, what we need from you, and what follows.
AnswersWhat to send your compliance team or partner before you buy mortgage leads
A checklist a loan officer can forward: the consent wording and how it is recorded, the phone check, the agreement terms, the prices and the comparison, each with the page that shows it.
AnswersHow to check that a lead vendor never resells your leads
Ask for the clause, not the adjective. What a no-resale clause in a lead agreement should cover, and the one thing no clause can promise.